TMG Enterprise Partners offers independent brokerages infrastructure without the buyout
Launching this week, the platform targets independent mortgage professionals who operate under their own shingle but face the same compliance costs and technology overhead as a 50-person shop.
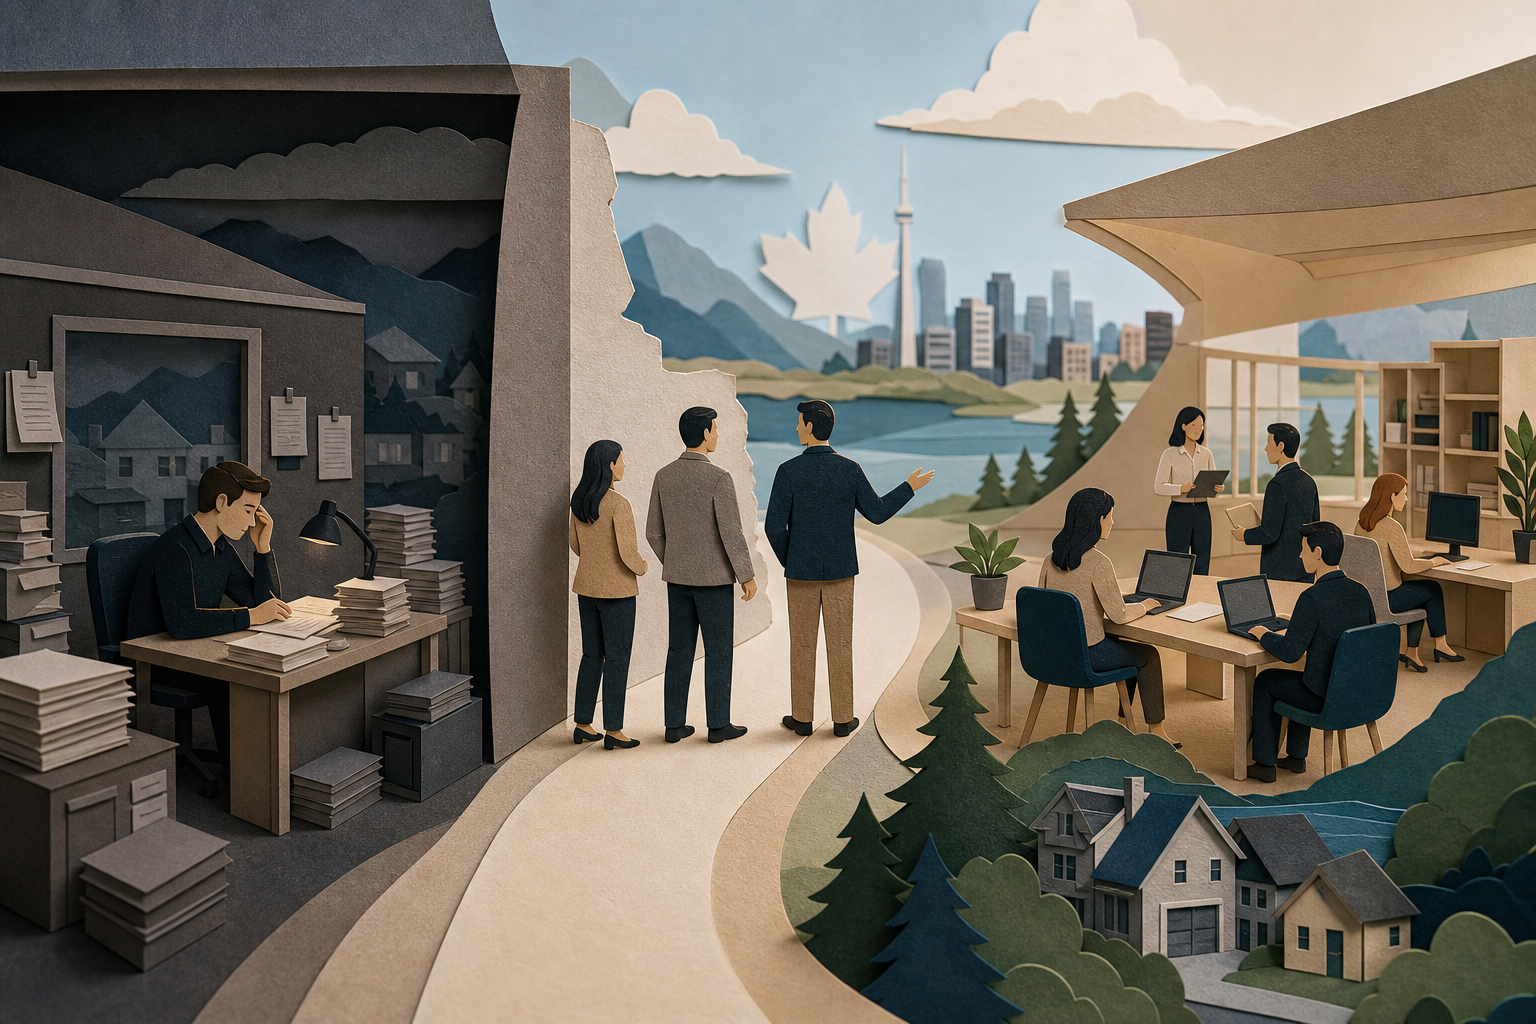
The pitch is straightforward. TMG Enterprise Partners supplies payroll, commission tracking, regulatory oversight, and access to proprietary tech stacks. The independent brokerage keeps its name, its owners, and its culture. No equity changes hands.
The structural problem this solves has intensified over the last three years. Stricter Anti-Money Laundering and Know Your Customer requirements mean a solo broker or a three-person office now needs either a part-time compliance officer or a standing relationship with a law firm that understands FSRA's audit expectations. Both cost more than the revenue on two or three closed files per month. Meanwhile, lenders increasingly tier their rates and approval speed by the volume a brokerage delivers network-wide, which puts independent shops at a disadvantage even when the individual broker has a pristine track record.
The sovereignty calculation
The traditional route for a small brokerage under this kind of pressure has been to join a franchise network. That usually means rebranding. The local firm becomes "[Franchise Name], [City] Office," the website changes, and the original owner becomes a branch manager in someone else's org chart.
TMG's model reverses that. The brokerage stays incorporated under its original name. The owner still signs the commission cheques. But behind the scenes, TMG handles the payroll processing, the quarterly compliance filings, and the integrations with document portals and CRM systems that would otherwise require a part-time IT contractor.
The appeal is less about cost savings, though those exist, and more about time recapture. A brokerage spending 12 hours per month on payroll adjustments, another eight on compliance documentation, and six chasing down a software vendor because a portal integration broke is spending 26 hours not generating leads. At $200 per hour of effective client-facing time, that's $5,200 monthly in opportunity cost. Over a year, $62,400.
Volume clout as a shared resource
TMG is one of Canada's largest brokerage networks. Participating firms gain access to that collective volume when negotiating with lenders. For rate-sensitive clients, network brokers may secure better pricing. On a $600,000 mortgage, even a modest rate advantage can translate to meaningful savings over a five-year term.
The platform also functions as a regulatory buffer. When a provincial regulator updates its audit checklist or introduces new compliance requirements, TMG's compliance team distributes the updated workflows to all partner firms quickly. An independent shop learning about the change from a broker forum weeks later is already behind.
The dependency tradeoff
The question is what happens when a brokerage wants to leave. Switching costs matter. If a firm's entire payroll system, compliance archive, and CRM integrations run through TMG's software, migrating to a different platform, or back to fully independent operations, means rebuilding all three. Rebuilding takes a two-month project minimum, and two months is a long time to operate with half your back-office systems offline.
TMG retains the brokerage's branding and client relationships, but not the operational continuity. A firm that grows beyond the platform's utility, or finds a better deal elsewhere, will face friction on the way out. That friction isn't lock-in, but it isn't nothing either.
For brokerages currently spending more time on compliance paperwork than client calls, the tradeoff makes sense. The platform doesn't eliminate the risk of dependency. It shifts that risk to a manageable scale in exchange for recovering the hours that actually generate revenue.

Launching this week, the platform targets independent mortgage professionals who operate under their own shingle but face the same compliance costs and technology overhead as a 50-person shop.
The pitch is straightforward. TMG Enterprise Partners supplies payroll, commission tracking, regulatory oversight, and access to proprietary tech stacks. The independent brokerage keeps its name, its owners, and its culture. No equity changes hands.
The structural problem this solves has intensified over the last three years. Stricter Anti-Money Laundering and Know Your Customer requirements mean a solo broker or a three-person office now needs either a part-time compliance officer or a standing relationship with a law firm that understands FSRA's audit expectations. Both cost more than the revenue on two or three closed files per month. Meanwhile, lenders increasingly tier their rates and approval speed by the volume a brokerage delivers network-wide, which puts independent shops at a disadvantage even when the individual broker has a pristine track record.
The sovereignty calculation
The traditional route for a small brokerage under this kind of pressure has been to join a franchise network. That usually means rebranding. The local firm becomes "[Franchise Name], [City] Office," the website changes, and the original owner becomes a branch manager in someone else's org chart.
TMG's model reverses that. The brokerage stays incorporated under its original name. The owner still signs the commission cheques. But behind the scenes, TMG handles the payroll processing, the quarterly compliance filings, and the integrations with document portals and CRM systems that would otherwise require a part-time IT contractor.
The appeal is less about cost savings, though those exist, and more about time recapture. A brokerage spending 12 hours per month on payroll adjustments, another eight on compliance documentation, and six chasing down a software vendor because a portal integration broke is spending 26 hours not generating leads. At $200 per hour of effective client-facing time, that's $5,200 monthly in opportunity cost. Over a year, $62,400.
Volume clout as a shared resource
TMG is one of Canada's largest brokerage networks. Participating firms gain access to that collective volume when negotiating with lenders. For rate-sensitive clients, network brokers may secure better pricing. On a $600,000 mortgage, even a modest rate advantage can translate to meaningful savings over a five-year term.
The platform also functions as a regulatory buffer. When a provincial regulator updates its audit checklist or introduces new compliance requirements, TMG's compliance team distributes the updated workflows to all partner firms quickly. An independent shop learning about the change from a broker forum weeks later is already behind.
The dependency tradeoff
The question is what happens when a brokerage wants to leave. Switching costs matter. If a firm's entire payroll system, compliance archive, and CRM integrations run through TMG's software, migrating to a different platform, or back to fully independent operations, means rebuilding all three. Rebuilding takes a two-month project minimum, and two months is a long time to operate with half your back-office systems offline.
TMG retains the brokerage's branding and client relationships, but not the operational continuity. A firm that grows beyond the platform's utility, or finds a better deal elsewhere, will face friction on the way out. That friction isn't lock-in, but it isn't nothing either.
For brokerages currently spending more time on compliance paperwork than client calls, the tradeoff makes sense. The platform doesn't eliminate the risk of dependency. It shifts that risk to a manageable scale in exchange for recovering the hours that actually generate revenue.
Sources
Read Next
Canada's U.S. Export Share Falls to 66%: What Three Decades of Trade Data Reveals About Dependency Risk
Toronto Sellers Could Regain Leverage This Fall Despite August Sales Drop
How US Tariffs Could Push Canadian Mortgage Rates Higher Through Four Indirect Channels
Canada's 50% Counter-Tariffs Hit U.S. Dairy and Steel: What the Retaliation Costs Your Supply Chain