How US Tariffs Could Push Canadian Mortgage Rates Higher Through Four Indirect Channels
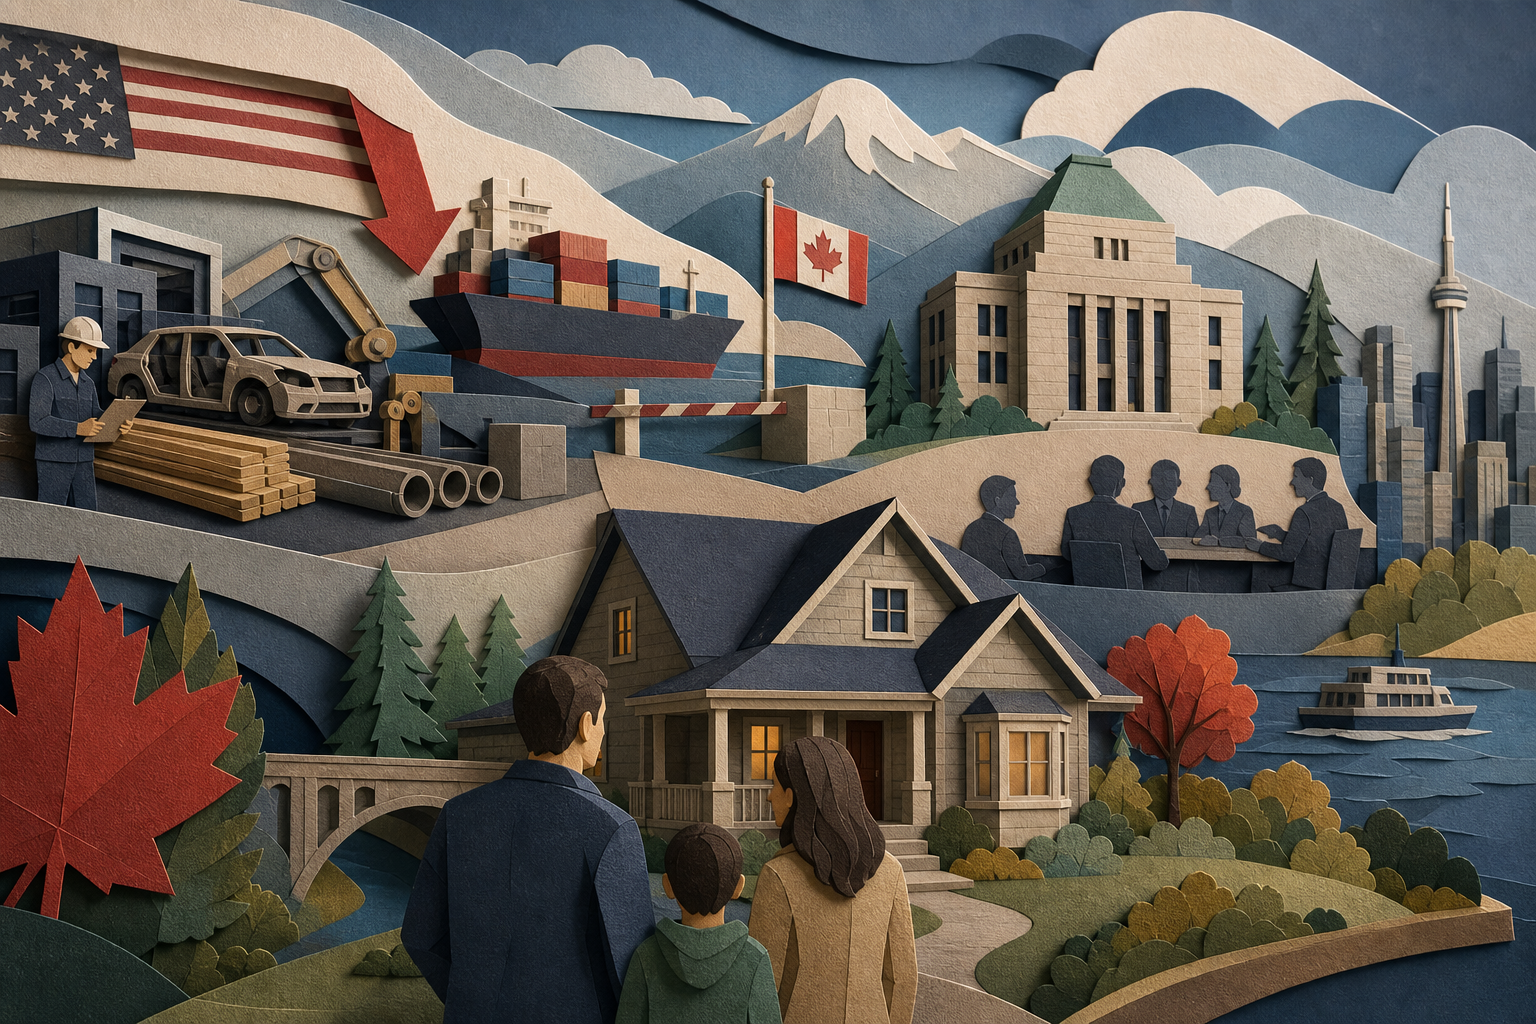
The Bank of Canada lowered its policy rate between June 2024 and January 2025, dropping it from 5.00% to 3.00%. Variable-rate mortgage holders celebrated. Then U.S. President Donald Trump threatened 25% tariffs on Canadian goods in February 2025, and the economic picture changed overnight. Canada retaliated with C$15.6 billion in duties on U.S. imports. The trade war was on.
What most borrowers miss is that tariffs do not affect mortgage rates directly. There is no lever connecting customs duties to bond yields. The effect runs through four separate mechanisms, each of which can push rates in opposite directions depending on which force dominates.
The Growth Channel Pulls Rates Down
Canada exports approximately 68% of its merchandise to the United States. A 25% tariff acts as a tax on every car part, barrel of oil, and sheet of softwood lumber crossing the border. U.S. buyers shift to cheaper suppliers. Canadian factories slow. GDP growth contracts.
When growth falls, the Bank of Canada responds by lowering its overnight rate to stimulate borrowing and spending. That lowers the Prime Rate, which variable-rate mortgages track directly. For fixed-rate mortgages, the transmission is less immediate. The 5-year Government of Canada bond yield tends to fall when investors expect a weaker economy, and fixed rates move with that yield. A recession-level slowdown could drop 5-year fixed rates by 50 to 100 basis points within six months.
The counterintuitive result: tariffs that hurt the economy can lower what you pay each month on your mortgage.
The Inflation Channel Pushes Rates Up
Tariffs raise the cost of imported goods. Canada buys machinery, electronics, food, and consumer products from the United States. When those goods carry a 25% duty, the price at the checkout rises. Inflation accelerates.
The Bank of Canada has a 2% inflation target. If tariffs push inflation above 3%, the central bank faces a choice: cut rates to fight the recession, or hold rates steady to prevent inflation from becoming entrenched. During the 1970s stagflation period, central banks chose inflation control over growth. Mortgage rates stayed high even as unemployment climbed. If the Bank of Canada prioritizes inflation today, variable rates could remain elevated or rise further despite economic weakness.
The Currency Channel Adds Import Costs
Tariffs weaken the Canadian dollar. Exporters earn less. Foreign investors pull capital out of Canada. The loonie falls from, say, 72 cents U.S. to 68 cents. That four-cent drop makes every imported product more expensive in Canadian dollar terms, even before tariffs are applied.
A weaker dollar feeds inflation directly. Groceries cost more. Electronics cost more. Fuel costs more. The weaker currency amplifies the inflationary pressure that keeps rates from falling, looping back into the inflation channel above and complicating the Bank of Canada's ability to cut rates.
The Safe-Haven Channel Compresses Fixed Rates
During extreme trade uncertainty, global investors flee to government bonds. Canadian 5-year bonds are considered low-risk. Demand rises. Yields fall. Fixed mortgage rates, which track those yields, drop.
This happened in March 2020 when COVID-19 hit. It happened again during the 2008 financial crisis. In both cases, bond yields plunged even as economic fundamentals deteriorated. The safe-haven effect can override the inflation channel entirely for a period of weeks or months, creating a window where fixed rates become unusually cheap.
The catch: this channel is timing-dependent. If you lock in a fixed rate during the panic, you win. If you wait and the panic fades, yields reverse and rates rise again.
The 2026 USMCA Review Compounds Uncertainty
The U.S.-Mexico-Canada Agreement comes up for formal review in 2026. That review clause creates a predictable volatility event. Expect bond yields to swing as negotiations approach, regardless of the outcome. For mortgage shoppers, that means rate unpredictability stretching through the next 18 months.
Which channel dominates depends on how severe the tariffs are, how long they last, and whether retaliation escalates. The growth channel and safe-haven channel push rates down. The inflation and currency channels push rates up. All four operate simultaneously. When they collide, the outcome is unpredictable.

The Bank of Canada lowered its policy rate between June 2024 and January 2025, dropping it from 5.00% to 3.00%. Variable-rate mortgage holders celebrated. Then U.S. President Donald Trump threatened 25% tariffs on Canadian goods in February 2025, and the economic picture changed overnight. Canada retaliated with C$15.6 billion in duties on U.S. imports. The trade war was on.
What most borrowers miss is that tariffs do not affect mortgage rates directly. There is no lever connecting customs duties to bond yields. The effect runs through four separate mechanisms, each of which can push rates in opposite directions depending on which force dominates.
The Growth Channel Pulls Rates Down
Canada exports approximately 68% of its merchandise to the United States. A 25% tariff acts as a tax on every car part, barrel of oil, and sheet of softwood lumber crossing the border. U.S. buyers shift to cheaper suppliers. Canadian factories slow. GDP growth contracts.
When growth falls, the Bank of Canada responds by lowering its overnight rate to stimulate borrowing and spending. That lowers the Prime Rate, which variable-rate mortgages track directly. For fixed-rate mortgages, the transmission is less immediate. The 5-year Government of Canada bond yield tends to fall when investors expect a weaker economy, and fixed rates move with that yield. A recession-level slowdown could drop 5-year fixed rates by 50 to 100 basis points within six months.
The counterintuitive result: tariffs that hurt the economy can lower what you pay each month on your mortgage.
The Inflation Channel Pushes Rates Up
Tariffs raise the cost of imported goods. Canada buys machinery, electronics, food, and consumer products from the United States. When those goods carry a 25% duty, the price at the checkout rises. Inflation accelerates.
The Bank of Canada has a 2% inflation target. If tariffs push inflation above 3%, the central bank faces a choice: cut rates to fight the recession, or hold rates steady to prevent inflation from becoming entrenched. During the 1970s stagflation period, central banks chose inflation control over growth. Mortgage rates stayed high even as unemployment climbed. If the Bank of Canada prioritizes inflation today, variable rates could remain elevated or rise further despite economic weakness.
The Currency Channel Adds Import Costs
Tariffs weaken the Canadian dollar. Exporters earn less. Foreign investors pull capital out of Canada. The loonie falls from, say, 72 cents U.S. to 68 cents. That four-cent drop makes every imported product more expensive in Canadian dollar terms, even before tariffs are applied.
A weaker dollar feeds inflation directly. Groceries cost more. Electronics cost more. Fuel costs more. The weaker currency amplifies the inflationary pressure that keeps rates from falling, looping back into the inflation channel above and complicating the Bank of Canada's ability to cut rates.
The Safe-Haven Channel Compresses Fixed Rates
During extreme trade uncertainty, global investors flee to government bonds. Canadian 5-year bonds are considered low-risk. Demand rises. Yields fall. Fixed mortgage rates, which track those yields, drop.
This happened in March 2020 when COVID-19 hit. It happened again during the 2008 financial crisis. In both cases, bond yields plunged even as economic fundamentals deteriorated. The safe-haven effect can override the inflation channel entirely for a period of weeks or months, creating a window where fixed rates become unusually cheap.
The catch: this channel is timing-dependent. If you lock in a fixed rate during the panic, you win. If you wait and the panic fades, yields reverse and rates rise again.
The 2026 USMCA Review Compounds Uncertainty
The U.S.-Mexico-Canada Agreement comes up for formal review in 2026. That review clause creates a predictable volatility event. Expect bond yields to swing as negotiations approach, regardless of the outcome. For mortgage shoppers, that means rate unpredictability stretching through the next 18 months.
Which channel dominates depends on how severe the tariffs are, how long they last, and whether retaliation escalates. The growth channel and safe-haven channel push rates down. The inflation and currency channels push rates up. All four operate simultaneously. When they collide, the outcome is unpredictable.
Sources
Read Next
Canada's U.S. Export Share Falls to 66%: What Three Decades of Trade Data Reveals About Dependency Risk
Toronto Sellers Could Regain Leverage This Fall Despite August Sales Drop
Canada's 50% Counter-Tariffs Hit U.S. Dairy and Steel: What the Retaliation Costs Your Supply Chain
Why the Bank of Canada will hold rates at 2.25% despite a trade war