How a basement suite cuts your mortgage payment: Ontario conversion costs and rental income compared
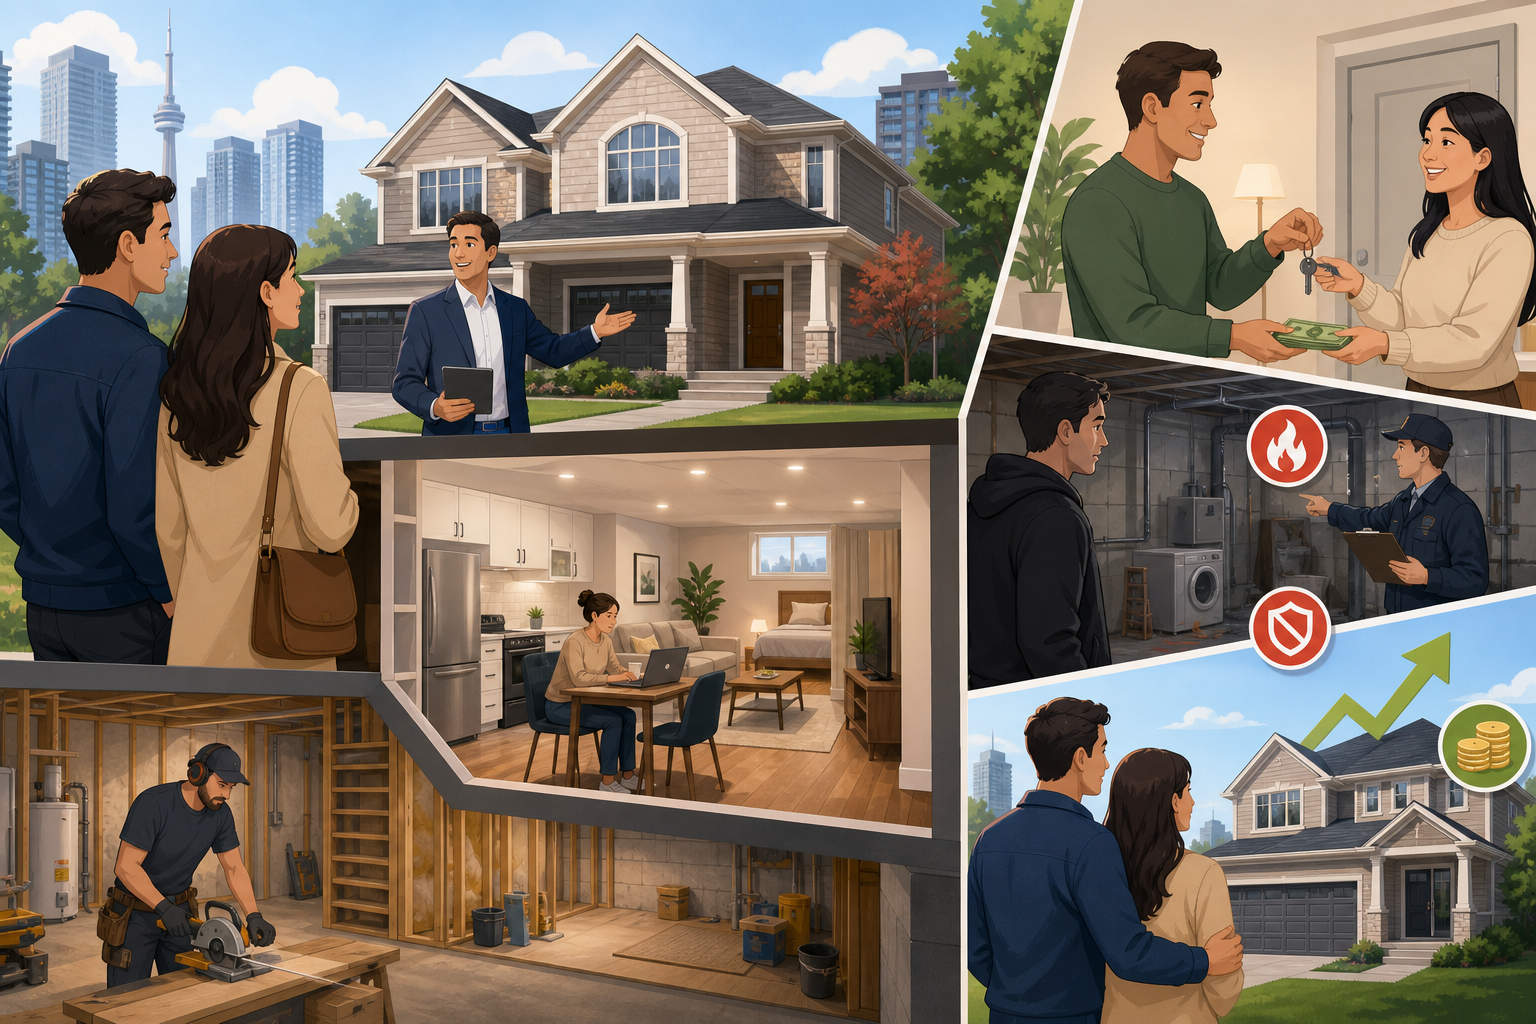
A $750,000 house in Mississauga becomes a $750,000 house you can actually qualify for when it includes a legal $2,000-per-month basement suite. The difference isn't the property. It's the debt-service math.
Canadian lenders allow 50% to 70% of gross rental income from a legal suite to count toward your qualifying income. On a $2,000-per-month suite, that's $12,000 to $16,800 of additional annual income the bank will use to calculate how much mortgage you can carry. For a buyer earning $90,000, that rental offset can be the difference between qualifying for a $600,000 loan and qualifying for an $800,000 loan.
The upfront cost is high, but the payback math is straightforward
A basement conversion in Ontario runs $80,000 to $150,000 in 2026, depending on whether you're starting with a roughed-in space or a full-height unfinished basement that needs windows, egress, plumbing rough-in, and fire-rated drywall. A detached garden suite or laneway house typically exceeds $200,000.
The Ontario Building Code and Fire Code dictate what makes a suite legal: minimum 6'5" ceiling height in most rooms, bedroom windows sized for emergency egress, fire separation between units using Type X drywall, and a separate entrance. These aren't negotiable. An "in-law suite" with a kitchenette and shared laundry hookup won't pass muster with lenders or insurers.
Most buyers finance the conversion into the purchase mortgage or complete it post-closing using a HELOC. At current rates, borrowing $120,000 at 6.5% adds roughly $775 per month to your payment. A $2,000 suite covers that cost and nets $1,225 monthly. That net return is what cuts the effective carrying cost of the house.
The rental income doesn't just help you qualify, it compounds equity
Mortgage qualification is where the suite makes the most immediate difference, but the compounding happens in two places. First, that $1,225 monthly surplus pays down principal faster. On a 25-year amortization, an extra $1,200 per month cuts roughly 8 years off the mortgage. Second, when you sell, a house with a legal income suite commands a price premium. Investors and multigenerational buyers both bid higher for turnkey rental income.
The flip side is that rental income you report to the Canada Revenue Agency affects your principal residence exemption. If the suite occupies 30% of your home's square footage, you may owe capital gains tax on that 30% when you sell. The CRA allows you to avoid this by filing Form T2091 and claiming the full exemption for up to four years after conversion, but only if you move the suite back to personal use before sale or navigate the "ordinarily inhabited" rules. This is the part where most first-time landlords get surprised.
Landlording in Ontario means complying with the Residential Tenancies Act
The Residential Tenancies Act in Ontario is heavily pro-tenant. You cannot evict someone because you don't like them. You cannot raise rent above the provincially set guideline (2.1% for 2026) unless the unit is exempt or you apply for an above-guideline increase based on capital work. If a tenant stops paying, the Landlord and Tenant Board process to regain possession averages 4 to 6 months. During that time, you still owe the mortgage.
Vacancy is the other risk. A suite that sits empty for two months costs you $4,000 in lost income. If your mortgage payment was built on the assumption of rental offset, that vacancy comes directly out of your personal cash flow.
Toronto, Ottawa, and most Ontario municipalities have eliminated development charges for secondary suites, and the More Homes Built Faster Act allows up to three units as-of-right on single-family lots. The regulatory path is easier than it was in 2024. The construction cost and the tenant-landlord friction remain exactly what they were.

A $750,000 house in Mississauga becomes a $750,000 house you can actually qualify for when it includes a legal $2,000-per-month basement suite. The difference isn't the property. It's the debt-service math.
Canadian lenders allow 50% to 70% of gross rental income from a legal suite to count toward your qualifying income. On a $2,000-per-month suite, that's $12,000 to $16,800 of additional annual income the bank will use to calculate how much mortgage you can carry. For a buyer earning $90,000, that rental offset can be the difference between qualifying for a $600,000 loan and qualifying for an $800,000 loan.
The upfront cost is high, but the payback math is straightforward
A basement conversion in Ontario runs $80,000 to $150,000 in 2026, depending on whether you're starting with a roughed-in space or a full-height unfinished basement that needs windows, egress, plumbing rough-in, and fire-rated drywall. A detached garden suite or laneway house typically exceeds $200,000.
The Ontario Building Code and Fire Code dictate what makes a suite legal: minimum 6'5" ceiling height in most rooms, bedroom windows sized for emergency egress, fire separation between units using Type X drywall, and a separate entrance. These aren't negotiable. An "in-law suite" with a kitchenette and shared laundry hookup won't pass muster with lenders or insurers.
Most buyers finance the conversion into the purchase mortgage or complete it post-closing using a HELOC. At current rates, borrowing $120,000 at 6.5% adds roughly $775 per month to your payment. A $2,000 suite covers that cost and nets $1,225 monthly. That net return is what cuts the effective carrying cost of the house.
The rental income doesn't just help you qualify, it compounds equity
Mortgage qualification is where the suite makes the most immediate difference, but the compounding happens in two places. First, that $1,225 monthly surplus pays down principal faster. On a 25-year amortization, an extra $1,200 per month cuts roughly 8 years off the mortgage. Second, when you sell, a house with a legal income suite commands a price premium. Investors and multigenerational buyers both bid higher for turnkey rental income.
The flip side is that rental income you report to the Canada Revenue Agency affects your principal residence exemption. If the suite occupies 30% of your home's square footage, you may owe capital gains tax on that 30% when you sell. The CRA allows you to avoid this by filing Form T2091 and claiming the full exemption for up to four years after conversion, but only if you move the suite back to personal use before sale or navigate the "ordinarily inhabited" rules. This is the part where most first-time landlords get surprised.
Landlording in Ontario means complying with the Residential Tenancies Act
The Residential Tenancies Act in Ontario is heavily pro-tenant. You cannot evict someone because you don't like them. You cannot raise rent above the provincially set guideline (2.1% for 2026) unless the unit is exempt or you apply for an above-guideline increase based on capital work. If a tenant stops paying, the Landlord and Tenant Board process to regain possession averages 4 to 6 months. During that time, you still owe the mortgage.
Vacancy is the other risk. A suite that sits empty for two months costs you $4,000 in lost income. If your mortgage payment was built on the assumption of rental offset, that vacancy comes directly out of your personal cash flow.
Toronto, Ottawa, and most Ontario municipalities have eliminated development charges for secondary suites, and the More Homes Built Faster Act allows up to three units as-of-right on single-family lots. The regulatory path is easier than it was in 2024. The construction cost and the tenant-landlord friction remain exactly what they were.
Sources
Read Next
Canada's U.S. Export Share Falls to 66%: What Three Decades of Trade Data Reveals About Dependency Risk
Toronto Sellers Could Regain Leverage This Fall Despite August Sales Drop
How US Tariffs Could Push Canadian Mortgage Rates Higher Through Four Indirect Channels
Canada's 50% Counter-Tariffs Hit U.S. Dairy and Steel: What the Retaliation Costs Your Supply Chain